You’re in a Monday morning meeting, going through delivery targets with your team, when your phone rings. It’s your driver. His voice is shaky. One of your delivery trucks, the one carrying your biggest client’s order for the week, has just been hit at a signal on Sheikh Zayed Road. Your mind jumps straight to your fleet insurance policy and whether it’s actually going to cover this.
For a second, you don’t think about paperwork. You think about the money you put into this business. The client is waiting on the other end. The truck is sitting in traffic, damaged, going nowhere.
Then the practical questions hit. What do you do first? Who do you call? What happens to your fleet insurance now, and how fast can you actually get the vehicle back on the road?
This guide walks you through exactly that, from the moment of the accident to the day your claim is settled, so you’re not figuring it out for the first time while standing on a busy Dubai road.
What is Fleet Insurance, and Why Does It Matter?
Fleet insurance in the UAE covers multiple company-owned vehicles under a single agreement instead of insuring each van, truck or car separately. For an expat running a delivery service, a logistics company, or even a small trading business with three or four vehicles, this single policy usually means one renewal date, one insurer relationship, and one claims process to learn rather than five different ones.
That last part matters more than people realise when they’re setting up a business here. You don’t want to deal with four different insurers with four different claim numbers on the day something goes wrong.
Why is It Important in the UAE?
- Commercial vehicle insurance is a legal requirement to operate on UAE roads, and fleets are no exception.
- Traffic volumes in cities like Dubai, Abu Dhabi and Sharjah mean accident risk is a real operational cost, not a hypothetical one.
- A single unresolved claim can take a vehicle off the road for days, which directly affects deliveries, client commitments and revenue.
- Insurers assess risk differently for fleets versus single vehicles, so understanding your specific policy terms protects you from nasty surprises later.
None of this is complicated once you’ve been through it once. The trouble is most business owners only learn the process after their first accident, which is the worst possible time to be learning anything.
What to Do Immediately After a Fleet Vehicle Accident?
The first fifteen minutes after an accident set the tone for everything that follows. Get this part right, and the rest of the claim tends to move smoothly. Get it wrong, and you’ll spend weeks chasing documents you should have collected on day one. A reliable fleet insurance provider in the UAE can guide you through these early steps, helping you understand what needs to be reported and documented straight away.
Here’s what should happen, in this order.
Ensure Everyone is Safe and Contact Emergency Services
If it’s safe to do so, move vehicles clear of moving traffic. Call 999 if anyone is injured, and 998 for an ambulance where needed. This sounds obvious, but under stress, drivers sometimes call their manager before checking on the other party involved. Safety comes before the insurer, before the photos, before anything else.
Report the Accident to the UAE Authorities
For most road accidents in the UAE, you’ll need an official police report, and the exact process can vary slightly depending on the emirate and how serious the incident is. In many cases, minor accidents without injuries can be reported and processed relatively quickly through the relevant traffic police channels, while more serious incidents involve police attending the scene directly.
This report matters because insurers rely on it as an independent record of what happened. Without it, your claim can be delayed or face additional questions later.
Collect Evidence at the Scene
While waiting for the police or after the report is filed, have your driver document everything:
- Vehicle damage from multiple angles
- The accident location and surrounding road layout
- Other vehicles involved, including number plates
- Road conditions, signage or anything relevant to how the accident happened
- Contact and insurance details of the other party
Fleet managers who’ve handled a few claims will tell you the same thing: don’t let the vehicle go straight to a garage before this is done. Once damage is repaired or the scene is cleared, that evidence is gone, and insurers sometimes ask for it weeks into the process.
Notify the Fleet Insurer
Every driver in your fleet should know exactly who to call and what to say. This is worth putting in writing, even a one-page instruction sheet in the vehicle, because in the panic of an accident, people forget steps.
Notify your insurer as soon as reasonably possible, ideally the same day. Most fleet policies specify a notification window, and delays can complicate what should otherwise be a straightforward claim. Once the scene is handled and the insurer knows what happened, the actual claims process begins.
An accident involving a company vehicle isn’t just about the vehicle. If your driver is injured on the job, that’s a separate liability altogether, one that falls outside your fleet policy entirely. This is exactly where protecting your employees becomes just as important as protecting your vehicles, and it’s worth understanding before an incident forces the question.
How to File a Commercial Fleet Insurance Claim Step by Step?
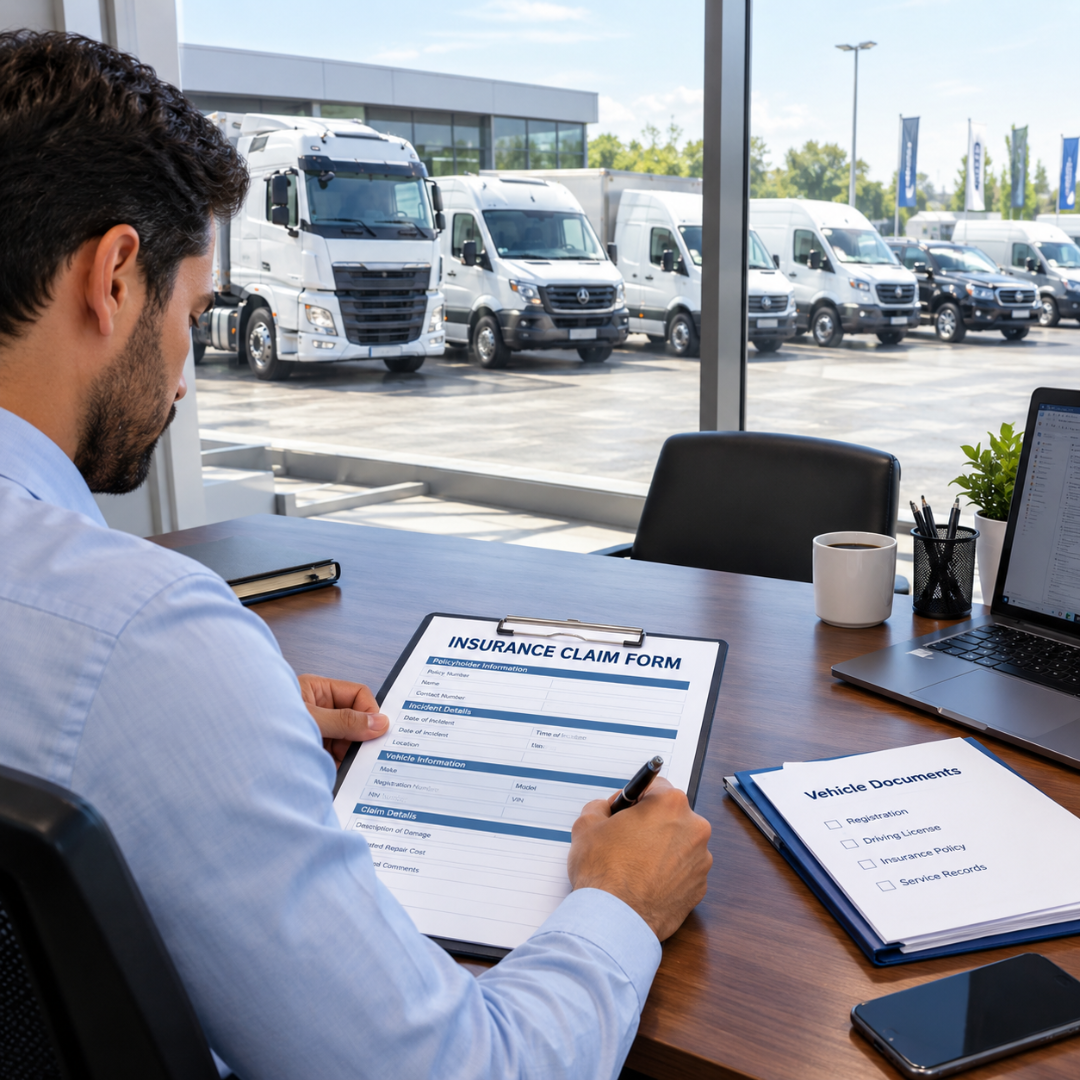
This is the part most business owners find genuinely confusing the first time around, mainly because it involves paperwork from three different sources: the police, the insurer, and your own internal records. Once you’ve done it once, it becomes fairly routine.
Step 1: Check Your Fleet Insurance Policy
Before submitting anything, pull out your fleet insurance policy in the UAE and check what it actually covers. Look specifically at:
- Whether you have comprehensive or third-party cover
- Accident damage, theft and fire provisions
- Any driver-related conditions, such as age or licence requirements
- Your excess or deductible amount
- Approved garage requirements
- Exclusions that might apply to this specific incident
This step gets skipped more often than it should. Understanding your coverage upfront tells you whether the incident is likely to be covered, and it saves you from assuming a payout that never comes.
Step 2: Prepare the Required Documents
Requirements vary by insurer, but you’ll typically need:
- Insurance policy details and vehicle registration
- The police or accident report
- Driver’s licence and Emirates ID (or equivalent identification)
- Photographs of the damage
- Repair estimates or garage documentation
- A completed claim form
- Any additional documents specifically requested by your insurer
What Documents Are Required for a Fleet Insurance Claim in the UAE?
Generally, insurers ask for the police report, vehicle and driver documents, photographic evidence, and a completed claim form, though the exact list depends on your policy and insurer.
Step 3: Submit the Claim to Your Insurer
- Most UAE insurers now accept claims online, by phone, or through a dedicated claims portal. Whichever route you use, be precise about what happened.
- Vague or inconsistent details tend to trigger follow-up questions that slow everything down.
- Attach every supporting document you gathered, and keep copies of all of it for your own records, including timestamps of when you submitted them.
Step 4: Cooperate With the Insurer’s Assessment
- The insurer will review the incident and may send a surveyor to inspect the vehicle, particularly for significant damage.
- Resist the urge to authorise major repairs before you’ve received clear instructions from the insurer.
- Doing so, even with good intentions, can complicate reimbursement if the repair scope doesn’t match what the insurer’s assessment allows.
Step 5: Use an Approved Repair Facility
- Many fleet policies direct or strongly recommend specific approved garages. Using one usually smooths the authorisation process, since the insurer already has an established relationship with that workshop.
- If the vehicle isn’t safe to drive, arrange towing through your insurer or roadside assistance rather than moving it independently.
Step 6: Track the Claim Until Settlement
- Keep your claim reference number somewhere accessible, and check in periodically rather than waiting for the insurer to reach out.
- Ask directly if anything is missing or pending approval.
- Keep a simple log of repair progress and correspondence dates.
- If things delay without explanation, that’s your cue to escalate.
With the paperwork in work, the next question most fleet managers ask is what actually happens on the insurer’s side.
What Happens After You Submit a Fleet Insurance Claim?
Once your claim for insurance for commercial vehicles lands with the insurer, it moves through a review process that determines whether, and how, it gets paid out.
Claim Review and Damage Assessment
The insurer examines the circumstances of the accident, checks it against your policy coverage, and reviews the supporting evidence you’ve submitted. Approval isn’t automatic. It depends on whether the incident falls within your policy terms and whether the documentation supports the claim as described.
Repair, Replacement or Claim Settlement
Depending on the extent of the damage, outcomes vary. Minor damage typically leads to authorised repairs at an approved garage. More severe cases, where the vehicle is deemed a total loss, may result in a settlement payout instead. Your excess or deductible will usually apply here, reducing the final amount payable, so it’s worth knowing that figure before you’re mid-claim and surprised by it.
Managing Fleet Downtime During the Claim
For delivery and logistics businesses especially, a vehicle sitting idle isn’t just an inconvenience. It’s lost revenue. If your business depends on a specific number of vehicles being operational daily, it’s worth having a contingency plan, whether that’s a short-term rental arrangement or reallocating routes among remaining vehicles. Track how long each vehicle stays off the road, patterns here often reveal whether your claims process needs tightening.
What to Do if Your Fleet Insurance Claim is Rejected or Delayed
Rejections happen, and they’re rarely without reason. Common reasons include policy exclusions, missing documentation, or a breach of policy conditions, such as an unlicensed driver at the time of the accident.
If this happens to you:
- Ask the insurer for the reason in writing
- Review your policy terms against that explanation
- Provide any additional documents or clarification requested
- Use the insurer’s formal complaints or escalation process if the explanation doesn’t hold up
- Seek professional advice if the dispute is significant enough to affect your business materially
Conclusion
Strip away the paperwork, and the process comes down to a simple sequence: stay safe, report the accident, gather evidence, notify your insurer, submit your documents, get through assessment, arrange approved repairs, and follow the claim to settlement.
If you’re an expat running a fleet here, the smartest move you can make isn’t waiting for the next accident to figure this out. Write a one-page accident procedure, give it to every driver, and keep it in the glovebox. It costs nothing and saves you the exact panic described at the start of this guide.
It’s also worth reviewing your fleet insurance policy every year or two, not just at renewal, to check whether your coverage, deductibles and approved garage network still match how your business actually operates. Businesses that aren’t sure whether their current policy offers adequate protection can have it reviewed by an insurance professional before an accident forces the question.